Exposure tells you how much market risk a holding carries.
LUSID's calculation of exposure for each instrument type is based on the commitment approach in the guidance provided by ESMA (the European Securities and Markets Authority). Where that guidance doesn't cover an instrument type, or its inputs aren't readily available, LUSID uses a calculation in the spirit of the guidance.
To report exposure for a holding when valuing a portfolio, include metrics such as (not a definitive list):
Valuation/Exposure: the holding's exposure in the currency the calculation uses (usually the instrument currency).Valuation/InstrumentExposure: the exposure of one unit of the instrument.Valuation/ExposureInPortfolioCcyandValuation/ExposureInReportCcy: the holding's exposure converted at the spot rate.Valuation/TotalPortfolioExposureInPortfolioCcyandValuation/TotalPortfolioExposureInReportCcy.Aggregation/NetExposureFractionandAggregation/GrossExposureFraction: total exposure, and total absolute exposure, as a fraction of total PV. Every holding must be in the same currency; otherwise LUSID returns no value.Aggregation/NetExposureWeightandAggregation/GrossExposureWeight: each holding's exposure, and absolute exposure, as a fraction of the portfolio's total PV, in the portfolio currency.Valuation/ExposureMSCI: exposure using the MSCI methodology.
Note the following:
You can call APIs in advance to understand which metrics might be useful or valid to include in a valuation report.
Some instrument types do not report exposure.
How LUSID calculates Valuation/Exposure
Every pricing model calculates the exposure of one unit of the instrument. LUSID then multiplies by the holding's units, so a short holding has a negative exposure. For a PIK bond, and for other bonds if you specify the fixedIncomeValuationsUsingCurrentFace recipe option, LUSID multiplies by the holding's current face instead.
For one unit, LUSID uses the first of these rules that applies:
The pricing model calculates exposure itself. Futures, options, contracts for difference, equity swaps and FX forwards work this way.
The instrument type has a notional. For an
InterestRateSwap,ForwardRateAgreement,CreditDefaultSwap,CdsIndex,CapFloor,TermDepositorFlexibleRepo, exposure is a notional or a cash amount, not a value.Otherwise, exposure is the value. For a
Bond,ComplexBondorInflationLinkedBondit is the PV. For other instrument types it is PV minus accrued interest, where appropriate.
Note the following:
Exposure isn't affected by an override of the holding's PV, clean PV or accrued interest. See how to override delta or exposure.
For an instrument that has matured, LUSID returns zero exposure if you specify the
returnZeroPv.instrumentMaturedrecipe option. Otherwise the valuation fails for that holding, as it does for PV.Some instruments can report each leg as a separate row if you specify the
produceSeparateResultForLinearOtcLegsrecipe option.
In the equations below:
Price is a quote's value divided by the quote's own
scaleFactor.Underlying price is the price of the instrument underneath a derivative: the equity for an equity option, the future for an option on a future, and so on. LUSID looks it up in the Quote Store.
Delta is the change in the option's value for a small change in the underlying price. It is between 0 and 1 for a call and between −1 and 0 for a put. In some circumstances you can override LUSID's delta with your own.
Equities
Instrument type (flavour) |
| Notes |
|---|---|---|
Equity (incl. ETF) |
| The calculation is the same as PV. |
| Under the
| |
| Under
| |
Future (equity, index, commodity, bond, and FX without a foreign currency) |
| |
|
| |
|
| |
| The full contract value, calculated with the ASX pricing formula, | |
| The full contract value | |
ExchangeTradedOption (equity, index, bond underlying) |
| |
|
| |
Under |
Under Note the |
Debt
The Valuation/Exposure calculation for the following instrument types is the same as PV:
BondComplexBond(including PIK and asset-backed)InflationLinkedBondBondForwardToBeAnnouncedToBeAnnouncedOptionBondOption
Rates
Instrument type (flavour) |
| Notes |
|---|---|---|
|
| |
InterestRateSwap (vanilla, basis, OIS, amortising, cross-currency) |
For a cross-currency swap with the | |
Under
| Other pricing models do not calculate exposure. | |
|
| |
|
|
Under the following pricing models, the calculation is the same as PV:
Note the |
|
|
Credit
Instrument type (flavour) |
| Notes |
|---|---|---|
|
| |
| ||
|
| The calculation is the same as PV. |
FX
Instrument type (flavour) |
| Notes |
|---|---|---|
FxForward (deliverable, NDF) | The amount of each leg that isn't in the exposure currency, ignoring its sign and converted to the exposure currency at spot, added together and | For a deliverable with the Under |
The exposure of the near forward plus the exposure of the far forward, calculated as for | Under | |
FxOption (vanilla) |
|
Under Note the |
Commodities
Instrument type (flavour) |
| Notes |
|---|---|---|
|
| The calculation is the same as PV. |
|
Volatility
Instrument type (flavour) |
| Notes |
|---|---|---|
|
| The calculation is the same as PV. |
Securitised finance
Instrument type (flavour) |
| Notes |
|---|---|---|
| ||
|
| The calculation is the same as PV. |
| The PV of the whole swap minus accrued interest (its clean PV), asset and funding legs together. Exposure is not the value of the underlying asset. | Under |
|
| The calculation is the same as clean PV. |
Instrument types with no exposure
LUSID does not calculate exposure for the following instrument type and pricing model combinations. The Valuation/Exposure metric is blank for these holdings.
FlexibleLoanandFlexibleDeposit, priced withFlexibleLoanPricer.LoanFacilityandWholeLoanFacility, priced withLoanFacilityPricer.CapitalInterest, priced withCapitalInterestPricer.InflationSwap, priced withInflationForwardorConstantTimeValueOfMoney.EquityOptionpriced withBjerksundStensland1993.FxOptionpriced withBachelier.InterestRateSwaptionpriced withConstantTimeValueOfMoney, or withDiscountingif the underlying swap has no single fixed rate.Any instrument priced with
OverrideOnly, unless you supply the exposure yourself.
Exposure using the MSCI methodology
The Valuation/ExposureMSCI returns exposure using the MSCI methodology. Note the following:
For an option with a premium, it is the PV, which under an option pricing model is the option's value minus the discounted premium.
For
ContractForDifferenceunderConstantTimeValueOfMoneyorDiscounting, it is the same asValuation/Exposure.It is blank for
FlexibleLoan,FlexibleDeposit,LoanFacility,WholeLoanFacilityandCapitalInterestpriced with their own pricing models.It can have a value where
Valuation/Exposureis blank, for example 0 for anInterestRateSwaptionpriced withConstantTimeValueOfMoney, or the PV for anFxOptionpriced withBachelier.
The Aggregation/*ExposureFraction and Aggregation/*ExposureWeight metrics each have an MSCI version, for example Aggregation/GrossExposureFractionMSCI.
Exposure in lookthrough portfolios
When LUSID looks through a holding to the portfolio underneath, the conservedQuantityForLookthroughExpansion recipe option decides what the expanded holdings preserve:
PV(the default): each underlying holding is valued as normal, so its exposure follows the rules in this article.Exposure: each underlying holding's exposure is its weight multiplied by the parent holding's exposure, in the report currency.
Overriding delta or exposure
You can load your own values into LUSID's Structured Result Store (SRS), and LUSID uses them instead of the values it calculates. Two addresses affect exposure:
UnitResult/Valuation/Deltareplaces the delta in the exposure calculation for anExchangeTradedOptionorEquityOptionpriced withSimpleStatic.UnitResult/Valuation/InstrumentExposurereplaces the exposure of one unit of the instrument for any instrument type.
LUSID applies the value it finds as it is. For a meaningful delta, use a number between −1 and 1 that is positive for a call and negative for a put.
Example: loading a delta into the SRS
To load a delta for an equity option:
Prepare a JSON or CSV document with a delta keyed by the LUID of the instrument, for example:
LUID
Delta
LUID_JKGH56FT
0.6
Call the CreateDataMap API to create a data map for the document. Map the LUID column to the
UnitResult/LusidInstrumentIdaddress and the Delta column to theUnitResult/Valuation/Deltaaddress:curl -X POST 'https://<your-domain>.lusid.com/api/api/unitresults/datamap/ExternalEquityOptionDeltas' -H 'Content-Type: application/json-patch+json' -H 'Authorization: Bearer <your-API-access-token>' -d '{ "MyDeltaDataMap": { "id": { "version": "1.0.0", "code": "DeltaDataMap" }, "data": { "dataDefinitions": [ { "address": "UnitResult/LusidInstrumentId", "name": "LUID", "dataType": "String", "keyType": "Unique" }, { "address": "UnitResult/Valuation/Delta", "name": "Delta", "dataType": "Decimal", "keyType": "Leaf" } ] } } }'Call the UpsertStructuredResultData API to upsert the document to the SRS with the
UnitResult/Analyticresult type:curl -X POST 'https://<your-domain>.lusid.com/api/api/unitresults/ExternalEquityOptionDeltas' -H 'Content-Type: application/json-patch+json' -H 'Authorization: Bearer <your-API-access-token>' -d '{ "first-item": { "MyDeltaDocument": { "source": "Client", "code": "DeltaDocument", "effectiveAt": "2024-08-31T00:00:00.0000000+00:00", "resultType": "UnitResult/Analytic" }, "data": { "documentFormat": "Csv", "version": "1.0.0", "name": "My delta document", "document": "LUID,Delta\nLUID_JKGH56FT,0.6", "dataMapKey": { "version": "1.0.0", "code": "DeltaDataMap" } } } }'Call the UpsertConfigurationRecipe API to create a recipe, or amend an existing one, with a
pricing.resultDataRulesobject that locates the document in the SRS:curl -X POST 'https://<your-domain>.lusid.com/api/api/recipes' -H 'Content-Type: application/json-patch+json' -H 'Authorization: Bearer <your-API-access-token>' -d '{ "MyRecipe": { "scope": "ExternalEquityOptionDeltas", "code": "SRSRecipe", "pricing": { "resultDataRules": [ { "resourceKey": "UnitResult/*", "supplier": "Client", "dataScope": "ExternalEquityOptionDeltas", "documentCode": "DeltaDocument", "quoteInterval": "1M.0D", "documentResultType": "UnitResult/Analytic", "resultKeyRuleType": "ResultDataKeyRule" } ] } } }'
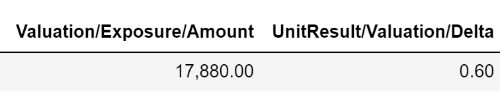
When you value the portfolio, LUSID calculates Valuation/Exposure with the delta from the SRS. Include Valuation/Delta to see the delta it used:
curl -X POST 'https://<your-domain>.lusid.com/api/api/aggregation/$valuation'
  -H 'Authorization: Bearer <your-API-access-token>'
  -H 'Content-Type: application/json-patch+json'
  -d '{
    "portfolioEntityIds": [ {"scope": "EquityOptions", "code": "UK"} ],
    "valuationSchedule": {"effectiveAt": "2024-08-31T00:00:00.0000000+00:00" },
    "recipeId": {"scope": "ExternalEquityOptionDeltas", "code": "SRSRecipe"},
    "metrics": [
      {"key": "Instrument/default/Name", "op": "Value"},
      {"key": "Valuation/Exposure", "op": "Value"},
      {"key": "Valuation/Delta", "op": "Value"}
    ]
  }'